 By Meghna Sharma
“Best performing” is a moving target in mutual fund investing because rankings change as NAVs and market conditions change. Instead of relying on a static top-funds list, investors should focus on categories that suit SWPs, evaluate funds using relevant criteria, and check current performance data before investing.
What Is a Systematic Withdrawal Plan?
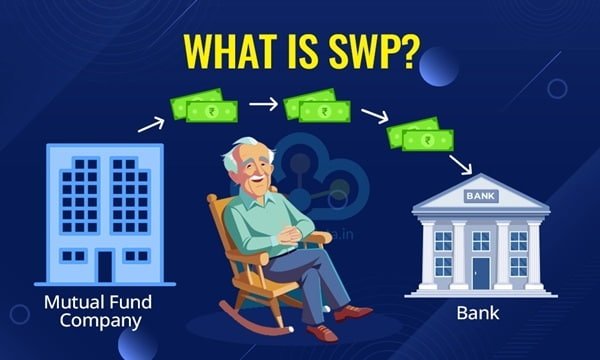
A Systematic Withdrawal Plan (SWP) allows investors to withdraw a fixed amount from a mutual fund at regular intervals, such as monthly, quarterly, or annually, while the remaining corpus stays invested. At each interval, the fund house redeems the required number of units and credits the withdrawal to the investor’s registered bank account.
An SWP is essentially the reverse of a SIP. It is commonly used by retirees, investors seeking supplementary income, and those who want regular cash flow without liquidating their entire portfolio at once.
Why SWPs Have Gained Popularity
Fixed deposits can provide stability, but their returns may struggle to outpace inflation over long periods. An SWP allows investors to generate regular cash flow while keeping the remaining corpus market-linked and potentially growing. This can make SWPs useful for retirement planning, where the objective is to create income without exhausting capital too quickly.
Fund Categories That Tend to Suit SWPs Best
The right category is often more important than chasing a fund with the highest recent return.
- Hybrid and balanced funds. Aggressive hybrid, conservative hybrid, and balanced advantage funds combine equity and debt. The equity portion offers growth potential, while debt can reduce volatility. This balance can be useful when investors depend on the corpus for regular withdrawals.
- Large-cap and flexi-cap equity funds. Investors with longer horizons and higher risk tolerance may consider established large-cap or flexi-cap funds for SWPs, provided the withdrawal rate remains conservative compared with expected long-term growth.
- Debt-oriented and conservative hybrid funds. Investors prioritizing capital stability, particularly those near or in retirement, may prefer high-quality debt or conservative hybrid funds. These generally offer lower volatility but also lower growth potential.
- Criteria Worth Evaluating Before Choosing an SWP Fund
- Rather than relying on a “top 10” ranking, evaluate candidate funds using several factors.
- Fund type and asset allocation. The equity-to-debt mix should match your risk tolerance and income horizon. A moderate hybrid allocation, such as 50:50 or 65:35 equity-to-debt, may provide a middle ground between growth and stability.
- AUM and liquidity. Larger funds with substantial AUM may handle recurring redemptions more smoothly than very small funds, particularly during periods of heavy withdrawals.
- Expense ratio. Costs reduce the amount available for long-term growth and withdrawals. When two funds have similar performance and risk, a lower expense ratio can improve efficiency.
- Downside behavior. Examine how a fund performed during previous market stress. An SWP investor sells units during withdrawals, so a sharp downturn can cause greater capital erosion than it would for someone still accumulating through a SIP.
- Long-term consistency. Review 3-year and 5-year CAGR along with performance consistency rather than focusing on one exceptional year. A stable record can provide more useful information than a temporary performance spike.
Understanding the Risk: Withdrawals Can Exceed Returns
SWPs carry sequence-of-returns risk: withdrawing during a market downturn can deplete the corpus faster than expected. Unlike a SIP investor, who may buy more units when prices fall, an SWP investor must sell units to fund withdrawals. Selling at depressed prices can accelerate capital erosion.
The commonly referenced “4% rule” suggests withdrawing roughly 4% of the corpus annually as a broad starting guideline. However, it should not be applied blindly. The appropriate withdrawal rate depends on the fund category, volatility, inflation, investment horizon, and personal income requirements.
Tax Treatment of SWP Withdrawals
Each SWP installment is treated as a redemption for tax purposes, with capital gains calculated according to the holding period of the units sold. For equity-oriented funds, long-term capital gains above the applicable annual exemption are taxed at the prevailing long-term rate, while short-term gains are generally taxed at the applicable short-term rate. Debt-oriented funds follow different taxation rules depending on their classification and acquisition date. Investors should therefore understand the specific fund’s tax treatment before setting a withdrawal schedule.
Direct vs. Regular Plans for SWP
Direct plans do not include distributor commissions and generally have lower expense ratios, which can improve long-term net returns. They may suit investors who are comfortable researching and managing their own investments.
Regular plans include distributor or advisor commissions but can provide ongoing guidance and support. This may be valuable for investors who prefer professional assistance, especially when managing retirement income.
How to Find Current Top-Performing Funds Yourself
Because rankings change, check current information before selecting a fund:
- AMFI: Use the official AMFI website for standardized mutual fund information across fund houses.
- AMC factsheets: Monthly factsheets provide current NAV, AUM, expense ratio, portfolio information, and performance data.
- Research platforms: Established mutual fund platforms can help compare funds by category, AUM, expense ratio, and multi-year returns.
Do not judge a fund solely by its latest return. Compare funds within the same category and examine risk, consistency, costs, and suitability for your withdrawal needs.
Final Thoughts
There is no permanently “best” SWP mutual fund. A fund that recently delivered the highest return may not be the most suitable for generating sustainable income. Investors should first select an appropriate category based on risk tolerance, time horizon, and withdrawal requirements, then evaluate individual funds for AUM, expense ratio, downside resilience, and consistent long-term performance.
Because market data changes frequently, verify current figures through AMFI, AMC factsheets, and reliable research platforms before investing. The goal of an SWP is not simply to maximize returns; it is to balance growth, stability, taxes, and withdrawals so the corpus can support income needs for as long as possible. This approach can make withdrawals more sustainable over time.